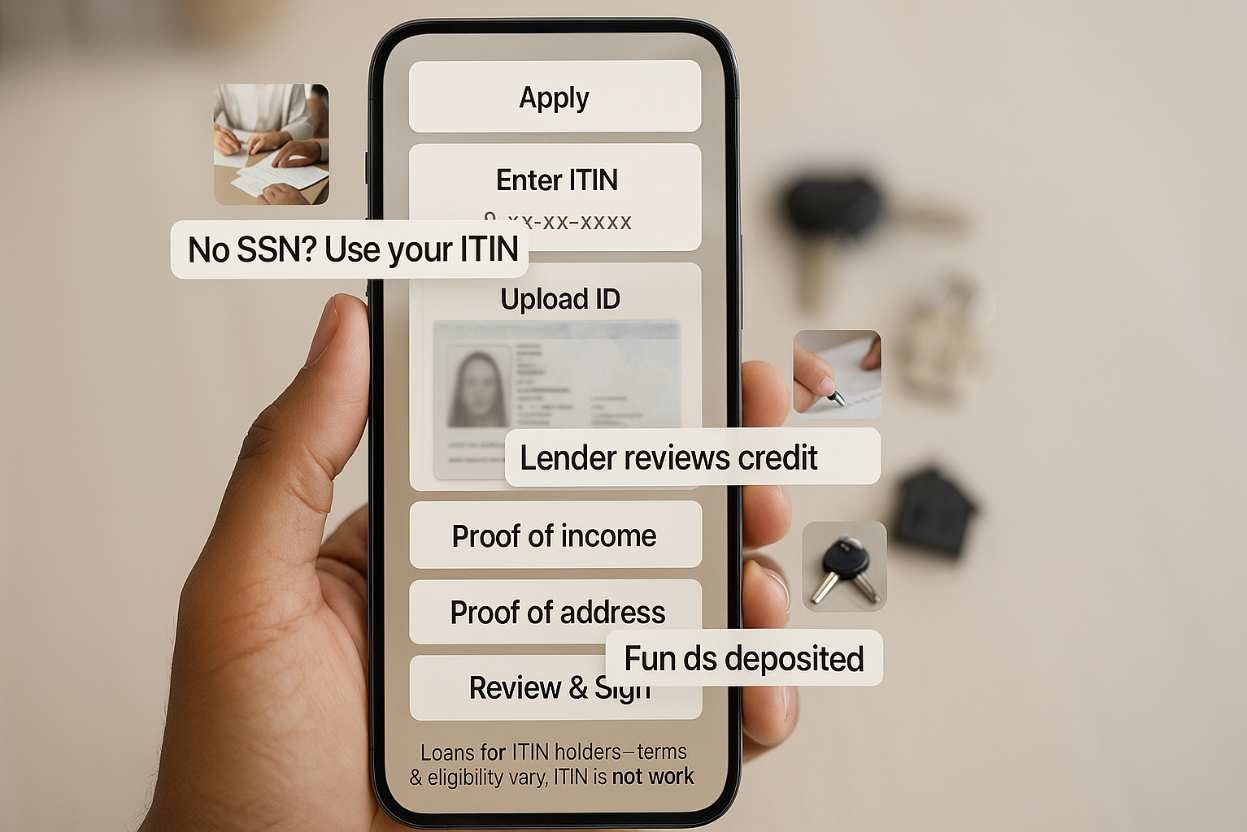
Getting loans with an ITIN number is possible even without a Social Security Number. Many lenders accept ITINs for personal loans, auto loans, and credit access. Our online guidance makes the process simple, secure, and error-free.
In this article, we will explore the different facets of loans for ITIN number holders, including how these loans work, their requirements, and where to find them.
How do ITIN loans work?
ITIN loans function similarly to traditional personal loans. Lenders provide funds to borrowers who may not qualify for conventional loans due to the lack of an SSN. Instead, they rely on the ITIN as a form of identification.
When applying for a loan, individuals with an ITIN must demonstrate their ability to repay the loan. This often involves providing proof of income, employment history, and residency documentation.
In many instances, lenders evaluate applications based on the borrower’s creditworthiness and financial history, which allows for a broader range of individuals to access credit. Loans for ITIN number holders can be used for various purposes, including debt consolidation, home improvements, and emergencies.
What is an ITIN?
An Individual Taxpayer Identification Number (ITIN) is a tax processing number issued by the IRS. It is specifically designed for individuals who are not eligible for a Social Security Number (SSN) but need to file taxes.
The ITIN is a nine-digit number that begins with the number 9 and is used primarily for tax reporting purposes. Obtaining an ITIN requires completing a W-7 form and providing necessary documentation, including proof of identity and foreign status.
While the ITIN is primarily utilized for tax purposes, it has become an essential tool for securing loans. Many lenders accept the ITIN when evaluating loan applications, fostering financial inclusivity for undocumented immigrants and others without an SSN.
What are the requirements for ITIN loans?
The requirements for securing loans for ITIN number holders can vary by lender, but generally, applicants must meet the following criteria:
- Valid ITIN: A valid Individual Taxpayer Identification Number is essential.
- Proof of identity: Borrowers must provide official identification, such as a passport or driver’s license.
- Proof of income: Documentation showing consistent income, such as pay stubs or tax returns, is often required.
- Residency documentation: Lenders may request proof of residence, such as utility bills or rental agreements.
Some lenders may also consider additional factors, such as credit history, debt-to-income ratio, and employment stability. Meeting these requirements can enhance the likelihood of securing a loan.
Where can you find ITIN loans?
There are various avenues for finding loans for ITIN number holders. Potential borrowers can explore options through:
- Credit unions: Institutions like Peninsula Credit Union often offer specialized loan products for ITIN holders.
- Online lenders: Many companies provide loans for ITIN number holders online, streamlining the application process.
- Local banks: Some banks may have specific programs catering to undocumented immigrants and those with ITINs.
- Community organizations: Various non-profits and community groups may offer resources or guidance on securing ITIN loans.
Researching different lenders and comparing their terms can help borrowers find the best personal loans with ITIN number options available in their area.
Can you buy a home with an ITIN?
Yes, it is possible to buy a home with an ITIN. Many lenders offer mortgage options specifically tailored for ITIN holders, allowing them to enter the housing market.
In order to qualify for a mortgage, ITIN holders must typically meet standard lending requirements, such as proof of income, creditworthiness, and sufficient down payment. Some lenders may also require additional documentation to verify employment and residency.
Moreover, borrowers with an ITIN can establish a credit history, which can improve their chances of securing favorable mortgage terms. A strong credit score can lead to lower interest rates and better financing options, making homeownership more attainable.
Alternatives to personal loans with an ITIN?
For those who may not qualify for traditional personal loans with an ITIN, several alternatives exist:
- Peer-to-peer lending: Platforms that connect borrowers with individual lenders can provide opportunities for ITIN holders.
- Secured loans: These loans require collateral, such as a vehicle or property, which can enhance approval chances.
- Credit-builder loans: These loans are designed to help individuals establish or improve their credit history.
- Community support programs: Local organizations may offer financial assistance or low-interest loans to individuals with an ITIN.
Exploring these alternatives can help individuals meet their financial needs without relying solely on traditional loan products.
Can undocumented immigrants build credit history?
Yes, undocumented immigrants can build credit history, primarily through the use of an ITIN. Many lenders and credit card companies accept ITINs as a form of identification, allowing these individuals to obtain credit products.
To establish a credit history, individuals should consider taking the following steps:
- Open a bank account: Starting a checking or savings account can help establish a relationship with a financial institution.
- Apply for a secured credit card: These cards require a cash deposit as collateral but can help build credit when used responsibly.
- Make timely payments: Consistently paying bills on time can positively impact credit scores over time.
Building a credit history is essential for gaining access to better loan options and improving financial stability in the long term.
Related questions about loans for ITIN number holders
Can I get a loan with ITIN?
Yes, obtaining a loan with an ITIN is possible. Many lenders are willing to offer personal loans for ITIN number holders, provided they meet specific requirements. The key is to demonstrate financial stability through proof of income, residency, and identification.
Additionally, it is crucial to research different lenders, as some may have more favorable terms than others. Taking the time to compare options can lead to better loan rates and repayment terms.
Can I buy a house with ITIN number in Illinois?
Yes, it is possible to buy a house with an ITIN in Illinois. Many lenders in the state offer mortgage products designed for ITIN holders, allowing them to purchase homes.
Just like any other borrower, ITIN holders must provide proof of income, maintain a good credit history, and demonstrate financial stability to qualify for a mortgage. Partnering with lenders experienced in working with ITIN borrowers can simplify the home-buying process.
What is the ITIN number in Virginia?
In Virginia, an Individual Taxpayer Identification Number (ITIN) serves the same purpose as in other states. It is a nine-digit number issued by the IRS to individuals who are not eligible for a Social Security Number (SSN) but need to file taxes.
The process for obtaining an ITIN in Virginia involves completing a W-7 form and submitting it to the IRS along with necessary documentation. An ITIN is essential for non-residents and residents alike, facilitating tax reporting and the ability to secure loans.